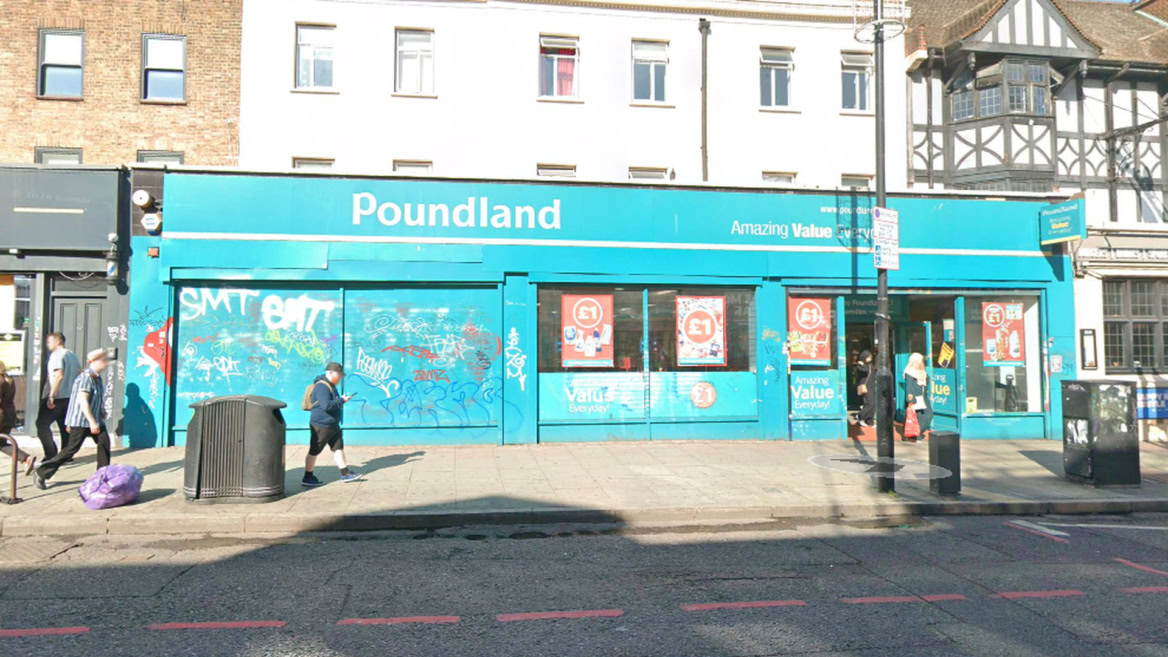
Poundland has been unable to pay suppliers for new stock since 27 October, after its owner Gordon Brothers restricted access to credit and trading cash, according to ITV News. The discount chain continues to sell existing stock while a notice of intention to appoint administrators runs to 12 November, with more than 10,000 jobs at stake.
Gordon Brothers bought Poundland from Pepco Group for £1 in June 2025, and the chain has since closed 115 shops as part of a restructuring programme. A staff memo seen by ITV News shows an unaudited swing in earnings before interest, tax, depreciation and amortisation (EBITDA) from a loss of £68.1 million in the financial year to September 2025 to a profit of £18.1 million in the year to September 2026, an improvement of £86.2 million. Retail Gazette reported the details on 9 November.
What the restrictions mean for the shelves
The restrictions mean Poundland can sell what it already holds but cannot replenish it. As of 3 November, the chain reportedly had about £25 million in cash that management could not access, even though the balance kept growing through shop sales. Martin Property Group, one of the bidders, has reportedly urged Gordon Brothers to release funding so that shelves can be restocked while rescue talks continue. Poundland has not been reported to have entered administration, and the stock restriction is the latest development after weeks of coverage of supplier credit and insurance cover.
Trading figures behind the memo
The memo reports like-for-like sales up 7% in the first period of the new financial year, and up 11.4% year on year in Halloween week, £1.5 million ahead of budget. Total sales remain below last year because of the shop closures. Barry Williams, managing director of Poundland, told ITV News on 4 November that he would fight until “the last minute” to save his colleagues. Gordon Brothers has taken a different view of the numbers: in a letter to the government, its UK operations boss Mark Newton-Jones said rising inflation, higher employment costs and shoplifting kept the business from generating cash at a sustainable level.
Bids and the 12 November deadline
Martin Property Group and Xyra Group Holdings have both submitted proposals to buy Poundland as a going concern. ITV News reported on 4 November that Xyra offered £12.5 million upfront towards repayment of a £30 million shareholder loan, against £5 million from Martin Property Group. Tesco, B&M, Iceland, Poundstretcher, The Range and Lidl have all expressed interest in parts of the estate. The Business and Trade Committee is due to hear evidence from company executives in private on Wednesday 11 November. The notice of intention to appoint administrators is due to expire on Thursday 12 November.
Good to know
A notice of intention to appoint administrators is a filing made ahead of an administration, not an administration itself. Retail Gazette reports that Poundland’s notice expires on 12 November, and no administration had been reported as of 9 November.
What happens next for the estate
The outcome of the week sets the future of the chain’s remaining shops and the roles attached to them. Xyra estimates that Poundland employs about 10,400 people across the UK and Ireland, with up to 30,000 further jobs tied to suppliers and logistics. Possible outcomes reported so far are a sale of the whole business as a going concern, a sale of parts of the estate to retailers such as Tesco or B&M, or an administration. Bid details and ownership statements have changed several times in recent weeks.